GLOBAL ECONOMY
China's Quiet Weapon: Rare Earths and Battery Supply Chains as the Biggest Bottlenecks for Global Industry in 2026
In October 2025, China expanded its rare earth export controls to 12 categories and introduced a 0.1% extraterritorial application, with many of the related measures suspended until November 10, 2026. Japan experienced actual, un-suspended controls, leading to sharp 88% and 82% declines in its rare earth imports from China in March and April respectively, with dysprosium and terbium imports dropping to virtually zero since January. Rare earth prices have surged since the beginning of the year, forming a "dual-market" structure where supplies sourced outside China command a 4 to 6 times premium over domestic Chinese prices. While MP Materials and Lynas have established initial milestones for a non-China supply chain, they are still far from sufficient to replace China's refining market share (approximately 91%). The South Korean battery industry must build the framework for alternative supply chains within this year, caught between a double deadline: the expiration of China's suspension on November 10 and the expiration of the US FEOC graphite suspension at the end of the year.
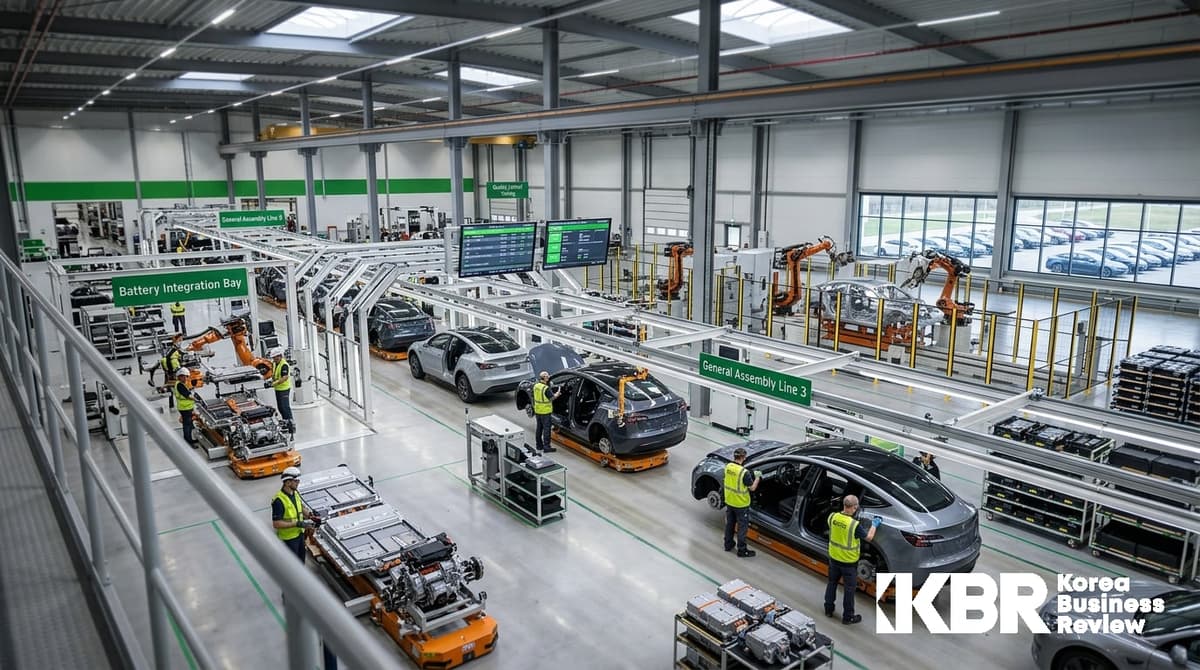
In October 2025, China expanded its rare earth export controls to 12 categories and introduced a 0.1% extraterritorial application, with many of the related measures suspended until November 10, 2026. Japan experienced actual, un-suspended controls, leading to sharp 88% and 82% declines in its rare earth imports from China in March and April respectively, with dysprosium and terbium imports dropping to virtually zero since January. Rare earth prices have surged since the beginning of the year, forming a "dual-market" structure where supplies sourced outside China command a 4 to 6 times premium over domestic Chinese prices. While MP Materials and Lynas have established initial milestones for a non-China supply chain, they are still far from sufficient to replace China's refining market share (approximately 91%). The South Korean battery industry must build the framework for alternative supply chains within this year, caught between a double deadline: the expiration of China's suspension on November 10 and the expiration of the US FEOC graphite suspension at the end of the year.
Export Licenses More Fearsome Than Tariffs… The Materials War Cutting Across EVs, Defense, Semiconductors, and Renewable Energy Executive Summary The greatest risk to global supply chains in 2026 is not tariffs, but materials.…
KBR Access
Global Radar content is available to Standard members and above
This content is available to Standard members and above. Standard unlocks general membership content including Insight 4.0, Policy Insight, and Global Radar.
FREE ACCOUNT · NO CARD REQUIRED
Create a free KBR account
Creating a KBR account is free and takes about a minute — no card required. You'll come straight back to this page once you're done.
KBR NEWSLETTER
Sign up for free and get the KBR Newsletter!
Sign up and opt in to the newsletter to receive KBR's curated business and economic insights by email.
LATEST IN TOPIC
Latest in this topic
 U.S. Manufacturing Hourly Compensation Rose While Unit Labor Costs Fell: Why They Must Be Read Together with Productivity
 Looking Only at Crude Prices Misses Fuel Costs: IEA Highlights Refined Product Bottlenecks and Corporate Procurement Choices
 Bank of Japan Decides to Raise Policy Rate to 1.25%: When Will Costs Change for Yen-Transacting Companies?
RELATED CONTENT
Related Content