ESG POLICY & STRATEGY
Carbon Footprint Is No Longer 'Feel-Good Marketing' — It Becomes a 'Second Cost' in 2026
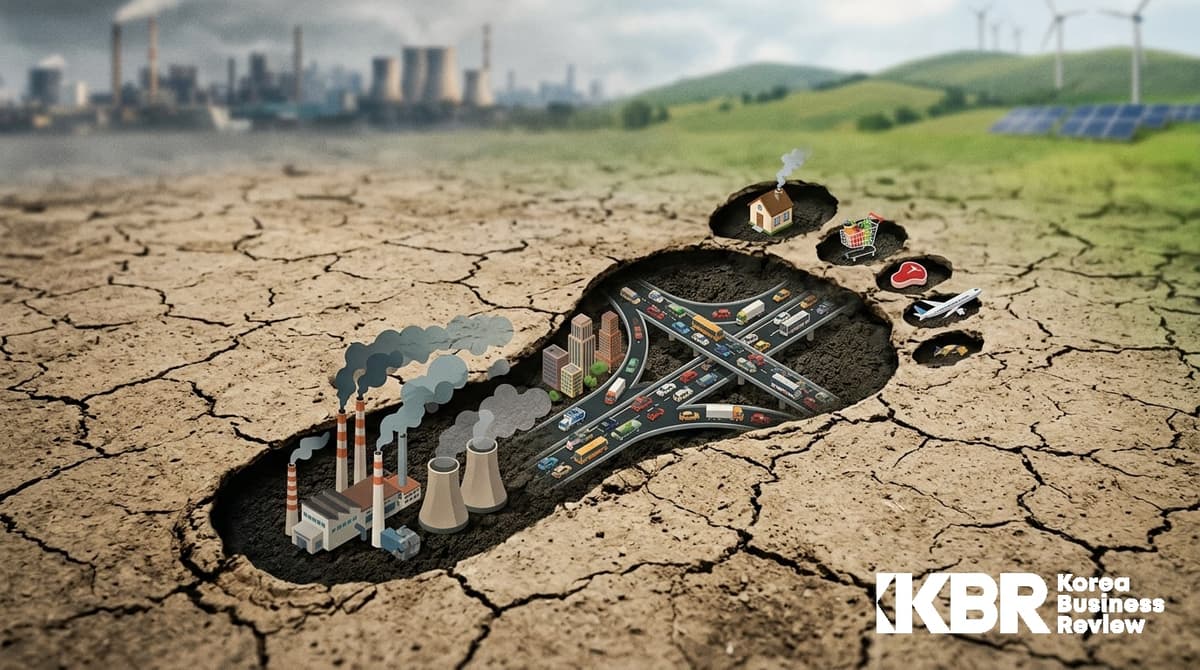
With the full implementation of the CBAM in January 2026 and the finalization of the KSSB in February, the carbon footprint has shifted from a 'measurement target' to an object of 'payment and reporting.' The EU CBAM imposes carbon costs on the import of six categories including steel and aluminum, with the certificate price for the first quarter announced at 75.36 euros per ton (April 2026). As the CSRD, Green Claims, and Digital Product Passport (DPP) intersect, regulatory focus is narrowing beyond company-wide levels to questioning the carbon of a 'single product' (PCF). South Korea will begin disclosures starting with KOSPI-listed companies with assets of 30 trillion won or more in 2028 (FY2027), while providing a three-year grace period until 2031 for Scope 3, which is the most challenging. Ultimately, companies equipped with verifiable carbon data infrastructure will reduce costs and gain bidding leverage, meaning the grace period is a 'preparation period,' not an 'exemption.'
With the full implementation of the CBAM in January 2026 and the finalization of the KSSB in February, the carbon footprint has shifted from a 'measurement target' to an object of 'payment and reporting.' The EU CBAM imposes carbon costs on the import of six categories including steel and aluminum, with the certificate price for the first quarter announced at 75.36 euros per ton (April 2026). As the CSRD, Green Claims, and Digital Product Passport (DPP) intersect, regulatory focus is narrowing beyond company-wide levels to questioning the carbon of a 'single product' (PCF). South Korea will begin disclosures starting with KOSPI-listed companies with assets of 30 trillion won or more in 2028 (FY2027), while providing a three-year grace period until 2031 for Scope 3, which is the most challenging. Ultimately, companies equipped with verifiable carbon data infrastructure will reduce costs and gain bidding leverage, meaning the grace period is a 'preparation period,' not an 'exemption.'
Carbon Footprint Is No Longer…
KBR Access
ESG content is available to Premium members only
This content is available exclusively to Premium members. Premium comes as a 1-month pass (₩34,900, one-time payment, no auto-renewal) or a monthly subscription (₩29,900/month) — both available via Toss Payments. Premium unlocks core content including ESG, KBR Articles, and KBR Analysis.
FREE ACCOUNT · NO CARD REQUIRED
Create a free KBR account
Creating a KBR account is free and takes about a minute — no card required. You'll come straight back to this page once you're done.
KBR NEWSLETTER
Sign up for free and get the KBR Newsletter!
Sign up and opt in to the newsletter to receive KBR's curated business and economic insights by email.
LATEST IN TOPIC
Latest in this topic
 EU Food Waste Reduction Targets: Food Companies Must Change the Structures That Cause Waste, Not Just Measure What Is Thrown Away
 Apple's 30% Recycled Materials: What Supply Chains Must Prove Beyond 'Eco-Friendly' Raw Materials
 Why UNEP's Redrawn 'Exceeding 1.5°C' Pathway Demands Corporate Climate Strategies Combine Mitigation and Adaptation
RELATED CONTENT
Related Content