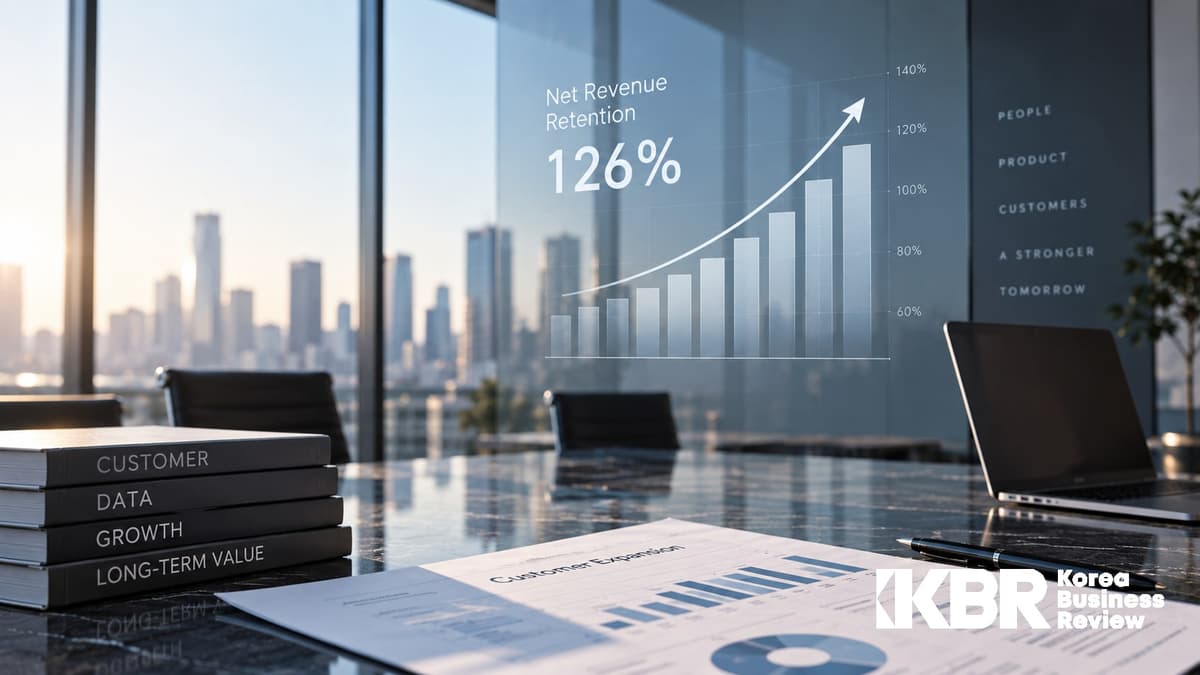
In Snowflake's financial results for the second quarter of fiscal year 2027 released on September 2, 2026, a figure of 126% appeared for the net revenue retention rate. If it represents the percentage of maintained customers, how can it exceed 100%? The answer lies in the word "revenue" within the term. The net revenue retention rate, or NRR, is an indicator that measures how the revenue generated from the same customer cohort changes, rather than tracking the number of existing customers. Even if some customers leave, NRR can exceed 100% if the purchases made by the remaining customers increase by a larger margin.
Conversely, even if the customer count remains unchanged, NRR can fall below 100% if the scale of purchases decreases. This means that customer retention and revenue retention are two different questions. To understand this metric, which is frequently used in subscription-based software and usage-based services, one must first look at which customers are fixed in the denominator before examining what revenues are placed in the numerator. Continuously adding new customers into the calculation obscures the objective of reading changes in existing relationships.
An Indicator Placing the Same Customer Cohort at Two Points in Time
The basic structure is a method that places the revenue of existing customers at a baseline period in the denominator, and the revenue generated by those same customers at a comparison period in the numerator. Additional purchases and upgrades by existing customers increase the numerator, while reduced usage and cancellations decrease it. Revenue from new customers is excluded from standard NRR calculations because it does not represent a change within the existing customer cohort. Here, the term "net" can be understood to mean that it reflects the combined effects of expansion and contraction.
Expressed in terms of recurring revenue, the structure involves taking the beginning recurring revenue, adding expansion revenue from existing customers, subtracting contraction and churn revenue, and dividing by the beginning recurring revenue. Multiplying the result by 100 yields the percentage. However, depending on the company, the monetary amounts and timeframes used vary—such as monthly recurring revenue, annual recurring revenue, or actual recognized product revenue. Even with the same name, there is no guarantee that the ingredients of the calculation are identical.
Assuming a company's situation, this difference becomes easily apparent. Suppose the monthly recurring revenue of a baseline customer cohort is 100 million won, and by the next comparison period, additional usage increased it by 30 million won, while reduced usage decreased it by 10 million won, and cancellations reduced it by 5 million won. The remaining monthly recurring revenue from the same customer cohort is 115 million won, resulting in an NRR of 115%. Revenue generated by new customers is not included in this calculation.
A result of 115% does not mean that all customers spent more. While some customers churned and others reduced their purchases, it means that expansion revenue outpaced those decreases. Furthermore, this ratio alone does not reveal how much the customer count has declined. It is possible that the departure of many small customers was offset by the expansion of a few large customers, or that most customers slightly increased their purchases. Different business structures can be contained within the same number.
How Customer Retention Rate Differs from Gross Revenue Retention

The customer count retention rate is the percentage of baseline customers who remain at the comparison period. If customers with large and small purchase amounts are each calculated as a single customer, they hold the same weight in terms of customer count even though their impact on revenue differs. Because NRR reflects the impact of revenue amounts, looking at both metrics together allows one to distinguish between the breadth of the customer base and the depth of revenue relationships.
GRR, referred to as gross revenue retention, typically excludes expansion revenue from existing customers and looks at losses from contraction and churn. In the previous example, if 15 million won was lost out of the 100 million won baseline due to contraction and churn, the GRR would be 85%. The same company can simultaneously record an NRR of 115% and a GRR of 85%. The former is the net result including expansion, while the latter shows how well the existing revenue base was preserved.
This combination creates distinct management questions. If NRR is high but GRR is low, one can examine whether the expansion of large customers is masking churn. If both metrics are stable, it may indicate a structure where losses from existing relationships are relatively small while additional purchases continue. However, there is no universal standard that a specific figure or higher guarantees a good business, as the context of comparison varies depending on pricing, contract duration, customer scale, and service maturity.
It also differs from the overall revenue growth rate. If new customers are added rapidly, overall revenue can grow even if existing customers' revenue declines. Conversely, even if NRR is high, overall growth speed may fall short of expectations if new customer inflows are weak or some contracts terminate. Therefore, NRR alone should not be used to explain the sales organization's new contract performance or the company-wide growth rate.
The Accurate Way to Read Snowflake's 126%
Snowflake's latest figure is based on the quarter ending July 31, 2026. The company sets a two-year measurement period, forming a cohort of capacity contract customers who used the platform in the first month of the first year. It then divides the product revenue of that same cohort in the second year by the product revenue of the first year. Customers who did not use the platform in the second year are not removed from the cohort and are instead reflected with zero revenue. End customers through resellers are also included, and adjustment rules for business combinations and spin-offs apply.
Therefore, 126% does not mean that the customer count increased by 26%, nor does it mean that the payment amount of all customers in that quarter increased by 26%. It is the result of comparing the annual product revenues of the existing customer cohort defined by the company. As such, when reading actual corporate figures, one must first verify the period, customer cohort, and revenue definition to properly interpret the numbers. It is also difficult to immediately treat an NRR calculated with monthly recurring revenue by another company as the same standard.
Snowflake explains that its product revenue is generated based on platform usage, unlike typical subscription models where contract amounts are recognized ratably over a period. For this reason, even if a customer's contract is maintained, product revenue can change according to actual usage patterns. While revenue expansion from existing customers is an important signal, it is not a number that directly guarantees nominal contract values or future usage.
The core lesson demonstrated by this case is that every company requires its own definition. Taking only the large headline number from a presentation introducing a metric easily leads to explaining the result of a two-year cohort comparison as if it were a quarterly retention rate. The more familiar the name, the easier it is to omit footnotes, yet the information needed to judge whether metrics are comparable actually lies within those definitions and footnotes.
Why High NRR Does Not Always Mean High Profitability
If existing customers use more, revenue may increase, but the cost of providing the service may also rise. In usage-based services, computing and storage costs, customer support, and third-party service costs may additionally occur. The mere fact that expansion revenue has increased does not mean that gross profit or cash flow has improved at the same rate. NRR is an indicator showing the persistence and expansion of revenue relationships, not a measure of profit margins.
Price increases can also elevate NRR. Even if existing customers use the same amount, revenue increases when unit prices rise. Conversely, if product efficiency improves and customers achieve the same results with lower usage, short-term revenue expansion may be weak even though customer value has improved. Revenue, usage, and actual business performance must be interpreted separately to avoid misjudging product value.
The drivers behind upgrades to higher pricing tiers or purchases of additional features also need to be segmented. The quality of the relationship can differ depending on whether customers expanded their purchases by broadening their operational scope or because previously included features were converted to separate billing. Revenue increases driven by the expiration of discounts are also a different signal from sustained usage expansion. Even with the same expansion amount, its predictive power for future renewals may vary.
Customer concentration is another interpretive variable. If increased usage by a single large customer pulls up the NRR of the entire cohort, the average may look favorable, but risk dispersion cannot be assumed. Breaking down metrics by customer scale and seeing where expansion amounts are concentrated helps provide a clearer understanding of the stability behind the same ratio. In this case, small cohorts can see their ratios shift dramatically based on changes in just one or two contracts, so numerical precision should not be over-trusted.
Common Errors in Calculation
The first error is excluding churned customers from the comparison cohort. If customers who were present at the baseline period are deleted simply because they generated no revenue at the comparison period, losses disappear and the retention rate is inflated. This is why the procedure of fixing customer identifiers and retaining cases where revenue is zero is crucial. A convenient approach that queries only currently active customers in the database may not align with the purpose of the metric.
The second error is mixing new customers into existing customer expansion. When corporate accounts are multiple or transactions go through resellers, a definition is required to determine whether a new account is genuinely a new customer or additional usage by an existing organization. If different standards are applied across sales teams, expansion performance and new contract performance can become swapped. Deciding whether the customer unit is an individual, account, legal entity, or corporate group must precede the calculation.
The third is the error of mixing timeframes. The beginning balance of monthly recurring revenue and actual cumulative revenue accumulated over a year cannot be placed into the same formula. For companies where contract renewals are concentrated in specific months, short-term figures can heavily reflect seasonal contract structures. Setting a comparison period too long can smooth out fluctuations, but creates a trade-off where recent changes are revealed slowly.
The fourth is the treatment of one-off amounts. Combining setup fees, training costs, and usage-dependent recurring amounts can cause a single large project to distort the retention rate. If the metric intends to track recurring revenue, the excluded amounts must be consistently defined. If the metric uses actual recognized revenue, it is important to clearly explain its scope and avoid calling it identical to recurring revenue-based metrics.
The fifth is exchange rates and organizational restructuring. Even if overseas customers' purchase volumes remain identical, changes in the reporting currency's exchange rate can cause revenue retention rates to shift. Cohort linkage methods also change when customer enterprises merge accounts or spin off business units. Rather than being targets for unconditional elimination, these changes require establishing treatment criteria aligned with the calculation's purpose and applying them consistently across periods.
Organizational Utilization Requires Preserving the Shifts Behind the Numbers
Useful reporting in practice illustrates the movement from beginning revenue through expansion, contraction, and churn to ending revenue. Even across two periods with identical NRR, the stability of relationships can differ between a period where expansion and churn both surged versus one where both were small. Reporting only the final ratio erases these distinctions. The net change in revenue and the movements occurring within it must be recorded together to determine subsequent actions.
Connecting the reasons for customer contraction to revenue data further enhances utility. Downsizing of user departments, budget changes, product issues, and changes in contract structures demand different responses. However, estimations by sales representatives and reasons directly confirmed by customers should not be treated as facts of the same caliber. Cases where the cause is unknown should remain unclassified and separated as targets requiring further verification.
Caution is also necessary when directly linking NRR to individual short-term evaluations. Maintaining contracts that are unsuitable long-term or inducing usage that customers do not need can improve short-term metrics while weakening relationships. Problems also arise when contributions from customer support and product enhancements are attributed solely to the performance of a single sales rep. Aligning the scope measured by the metric with the sphere actually controllable by team members is vital.
In management meetings, placing NRR alongside customer count retention rate, GRR, expansion revenue concentration, and service cost broadens the scope of interpretation. This combination does not necessarily need to be merged into a single composite score because these materials illustrate losses and opportunities from existing relationships from different angles. Which metric worsened while another improved can actually become a crucial talking point.
For companies calculating this for the first time, aligning the baseline customer roster and revenues across two periods takes precedence over complex dashboards. Verifying whether revenue totals match accounting data, whether churned customers remain, and whether new customers were excluded allows for the validation of significant portions of the formula. Afterward, it is more stable to categorize the causes of expansion and contraction and add necessary cohort-specific analyses.
Reasons must also be documented when revising historical figures of a metric. Interpretations vary depending on whether customer identification errors were corrected, business combinations were reflected, or the definition itself was altered. Connecting past and new figures without explanation can make trends look like actual business changes. Consistency in metrics stems not only from the ability to repeat calculations, but also from the capacity to explain audit trails of revisions.
An NRR of 100% signifies that the revenue of the existing customer cohort was maintained under the same criteria. Exceeding 100% means expansion outpaced losses, while falling below it indicates contraction and churn were greater. Additional evidence is required to read customer satisfaction, profitability, and future growth simultaneously beyond that point. A good metric is not one that says many things, but one that clearly defines what it says and what it does not say.
When explaining changes in revenue retention rates, percentages and percentage points must also be distinguished. How much the ratio itself rose versus how much it increased relative to the baseline ratio are different calculations. Omitting the unit of change for the same metric can make the magnitude of improvement sound larger than reality.
The value of the net revenue retention rate lies in revealing changes in existing relationships that are easily obscured behind the performance of acquiring new customers. It demonstrates that revenue can increase even when customer counts fall, and usage can decline even when contracts are maintained. To understand whether a corporation can grow long-term, one must look simultaneously at how many new relationships are built and what value is sustained within established connections. NRR is a tool that initiates that second question with concrete numbers.